Episode Highlights Here:
Intro
Before we jump into this episode, I want to invite you to join our community to help you become a better steward, scale to billions, and ultimately give more or all of it away. All I want
you to do is to click the subscribe button right now. I love your support. It’s incredible to see your comments, and we’re just getting started. I can’t wait to go on this journey with you.
Thank you so much for subscribing; it means the world to me.
Brett
Welcome to the Build it to Billions podcast, where we guide successful entrepreneurs and investors on their journey from millions to billions. We believe the key to scaling and compounding your wealth in life starts every single day with a mindset and practice of stewardship over ownership and applying billionaire biblical principles. Our ultimate goals have to be scale and compound your wealth in life, so you can give more all of it away to help MVPs. My name is Brett Swarts. Each and every episode, we’re joined by the world’s top entrepreneurs, real estate owners, investors, and they share their secrets with us and insights, so we can all level up and make a bigger impact. I’m excited about our next guest. He’s out of the Los Angeles area, and he’s the co-founder and leader of Convoy Home Loans, a California-based mortgage brokerage built to serve real estate investors, self-employed borrowers, and clients who often need financing beyond traditional loan programs. Convoy’s team page lists Jonathan as the COO, and the company’s mission is to provide homeowners and future homeowners with a variety of home financing options at competitive rates, and so much more. We’re talking about that today. Please welcome the show with me, Mr. Jonathan. You, Jonathan, how we doing?
Jonathan
I’m all right. Thanks for having us on.
Brett
Excellent. Yeah, and for our listeners getting to know you for the first time, would you give us just a little more about your story and your current focus?
Jonathan
Yeah, absolutely. So, we started the company, gosh, like almost six years ago now. Initially, that was think back, you know, five six years ago. Rates were in the ones, twos, threes, maybe at the highest point. My partner and I started the company, and we were like, we have to find a different avenue to be able to serve the underserved community, which at the time was investors, and there was no product for investment real estate as much as just qualifying off of bank statements or sorry tax returns and doing the loan based on that. A lot of investors were getting penalized and turned away from the banks. So, we said, hey, there has to bean other product that goes to service the real estate investor community without having to penalize them for being an investor and taking the tax loophole write-offs. So, what we did is we went out there, went to market, and we actually became one of the first brokers to bring the common what’s known as DSCR for residential properties to the residential market on a larger scale. So up until that point, again, think back in 2021, nobody was talking about DSCR, nobody was talking about being able to qualify for investment loans any other way other than tax returns and the Fannie Mae Freddie Mac way. So, what we did is we kind of brought that to you know main stage, really try to pump up that volume on that sense and bring awareness over to you. Don’t have to have perfect tax returns to be able to qualify for an investment property. You can qualify for an investment property by just using, you know, either the rental income of the property, or if you’re self-employed, you can still take all your write-offs and do a qualification based on, you know, bank statements or a profit and loss, some other way besides just going off tax returns. And I think that really changed the game for a lot of people, and now it’s obviously more mainstream. But this program has been around for the commercial real estate world for forever, right? Commercial real estate, anything above four units, always underwritten off of debt coverage, always. But this product was newly introduced into the market again five six years ago to the residential market, which is the one to four unit, which expanded the buy box for so many players because now they could buy that four unit in Ohio for 200 grand that cash flows you know really well and only put 20% down to buy it.
Brett
Okay, excellent. So that you guys were kind of cutting edge on the DCR and making sure that investors can buy and get access to financing and so give us the current status of where you feel the market is today. Housing market itself, debt and relative, and available financing. Like, what’s your sense in this? With like, you know, 10 being the best market, you know, to be able to be able to be a buyer with financing, and one being the worst. Where do you where do you sense that we’re at today, and what’s your sense on buyer sentiment to buy to buy new homes?
Jonathan
I think right now, the from a buying perspective, this is a nine or a 10 market, and I say that it’sa nine or a 10 market because everyone loves to buy when rates are low, and unfortunately,that also means that your buyer pool is really big, meaning you have a lot of competition,meaning you can’t work great deals in in better rate markets. So, in terms of buyers, nine outof 10 or 10 out of 10 for for investors trying to refinance, I’d probably say it’s maybe a seven oreight, right? And I say. Seven or eight because it allows you to tap into the equity, obviouslytax-free, right? To to pull out cash to buy properties if you have appreciating asset, or if you’reif you bought the property like three years ago, two years ago when rates were in the sevensand eights, and now everything’s averaging around the sixes, or we’re
Outro
So, if you like this little, short clip of the interview I just did, click over here to watch the full interview, and please don’t forget to subscribe. Thanks so much, everybody.
Watch the episode here:
Important Links:
About Jonathan Yoo
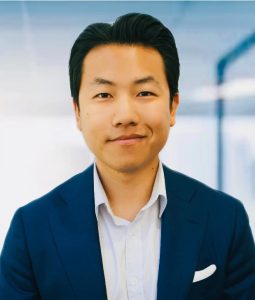
Jonathan Yoo is the COO and Principal of Convoy Home Loans, a mortgage brokerage specializing in financing solutions for homebuyers, real estate investors, and high-net-worth borrowers. With extensive experience in the mortgage industry, Jonathan has developed expertise in conventional, jumbo, Non-QM, DSCR, and investment-property financing.
Before helping build Convoy Home Loans, Jonathan led a team of 45 loan officers that funded more than $1 billion in loans in 2020. Today, he focuses on helping borrowers navigate complex financing scenarios while expanding Convoy’s presence in the real estate and mortgage markets. His experience gives him a unique perspective on interest rates, real estate investing, creative financing, and how investors can position themselves for opportunities across changing market cycles.
Love the show? Subscribe, rate, review, and share!
- capitalgainstaxsolutions.com
- Capital Gains Tax Solutions Facebook
- Capital Gains Tax Solutions Twitter
- Capital Gains Tax Solutions Tiktok